ALT-01 LUTVE
Vertical takeoff. Mach 6+. 100,000+ ft.
New York to Tokyo in 90 minutes.
DOCUMENT
Investor Overview
AL-EXD-001 · Issue 2 · October 2026
NEXT RAISE
$25–50M
Milestone-gated tranches
MATURITY
TRL 3 Today
Gate to TRL 4 · Q4 2027
ALTAREON GROUP · NEW YORK–TOKYO 90 MIN = MACH 6.5 CRUISE; VTOL ASCENT AND DESCENT ADD ~20 MIN · DESIGN TARGETS AT TRL 3 PER AL-EXD-001 ISSUE 2 · FORWARD-LOOKING STATEMENTS INVOLVE RISK.
The Problem · Why This Aircraft Must Exist
Aviation is running out of room.
A new machine is only worth building if it answers a question the world is already asking. These are the constraints closing in on air travel — each one measured, each one getting worse, and none of them solvable by the current fleet.
~882 Mt CO₂
emitted by aviation every year
Aviation produces roughly 2.5% of global CO₂ — about 882 million tonnes annually, and around 12% of all transport emissions. As other sectors decarbonize faster, aviation’s share of the problem is set to rise, not fall.
IEA · ATAG · Our World in Data
5.2B → 10B
passengers per year, by 2045
Roughly 5.2 billion people will fly in 2026. Airbus’ Global Market Forecast projects air traffic growing 3.9% annually — more than doubling to about 10 billion passengers a year within two decades.
Airbus GMF 2026–2045
15,400+ aircraft
in backlog — 11 to 12 years of production
Airbus and Boeing ended 2025 with a combined backlog above 15,000 aircraft, yet delivered only about 1,400 between them. At current rates, an airline ordering a new jet today waits more than a decade for it.
ADS · Forecast International
15.1 years
average fleet age — the oldest in history
Starved of deliveries, airlines are flying the oldest fleets aviation has ever recorded, up from 13 years before the pandemic, and extracting record utilization from aging airframes with higher fuel burn and maintenance burden.
IATA
$60B+
lost to disruption every year
Delays, cancellations, and operational friction cost the industry on the order of $60 billion a year globally — and the subsonic hub-and-spoke system that produces them is the only one the world has.
Industry disruption estimates
8–14 hours
to cross a single ocean
In a subsonic world the Pacific is a working day, and every long-haul route is chained to a long runway and a hub airport. Where the runways do not exist, the routes do not exist. Distance itself remains the constraint.
—
The Arc to ALT-01
Every number above is a wall. The torus is built to answer them.
01
Zero-carbon cruise
ALT-01 burns liquid hydrogen. Its exhaust is water — removing carbon from the cruise phase, the hardest segment of aviation to decarbonize, entirely.
02
No runways required
Vertical takeoff and landing cuts the tie between air routes and hub infrastructure. Routes follow demand — including regions conventional aircraft cannot economically serve.
03
Distance, collapsed
At Mach 6.5, New York to Tokyo is 90 minutes. The journey time stops being the constraint on what passengers, cargo, and emergency response can reach.
Sources: IEA · ATAG · Our World in Data · Airbus Global Market Forecast 2026–2045 · IATA · ADS · Forecast International · Oliver Wyman. ALT-01 performance figures are design targets at TRL 3.
Section 01 · Executive Summary
A position no aircraft program currently occupies — and a maturity stated plainly.
LUTVE is developing ALT‑01, a toroidal-geometry aircraft designed to combine vertical takeoff, Mach 6+ cruise, and 100,000+ ft ceiling on a single crewed, multi-mission airframe. New York to Tokyo in 90 minutes. No fielded or announced competitor combines all three capabilities. The program is at TRL 3, and the capital being raised funds the gate to TRL 4 — not a flying aircraft.
~44,000
new commercial aircraft needed by 2045
Boeing CMO 2026 — global fleet up ~80% to more than 50,000
$193B
global MRO spend by 2030, from $136B in 2025
Oliver Wyman Global Fleet & MRO Forecast 2026–2036
15,400+
jets in backlog — more than a decade to clear
Manufacturing capacity, not demand, is the binding constraint
$500M
raised by Hermeus, the category benchmark
$350M Series C, April 2026, at approximately $1B valuation
Why now
Demand is doubling, capacity is not
Boeing projects air travel will double over 20 years and the global fleet will grow nearly 80% to more than 50,000 aircraft by 2045 — requiring ~44,000 new deliveries. The commercial aviation services market alone is forecast at $4.9 trillion across 2026–2045. Yet 15,400+ jets sit in backlog: manufacturing capacity, not demand, is the binding constraint.
Source: Boeing Commercial Market Outlook 2026–2045
The high-speed segment has capital and a regulatory trail
Reusable launch reset what investors believe a vertically integrated aerospace company can achieve. Hermeus proved a high-speed airframe program can raise at scale and fly hardware — Mach 1.21 uncrewed, May 2026. Joby and Archer spent years forcing the FAA to build certification frameworks for aircraft that fit no existing category. That groundwork is a public good a later entrant inherits.
Source: Hermeus; FAA Part 23/SC-ADR pathway
Hypersonic is moving from military to commercial
The hypersonic flight market was $11.4B in 2025 and one forecast projects $120B by 2035 (26.5% CAGR). Military & defense holds 74.5% today; commercial travel is the fastest-growing segment. The DoD FY2026 request for hypersonic warfare programs is $13.4B, with $3.9B in hypersonic research — non-dilutive capital is real and available.
Source: Precedence Research; DoD FY2026 Budget Submission
Hydrogen propulsion is being de-risked in parallel
The hydrogen aircraft market is forecast from $7.4B (MarketsandMarkets, 2030) to $144B (2040), at 28–41% CAGR. Cryogenic storage, fuel cells, and airport supply chains are the adjacent infrastructure LUTVE inherits rather than invents.
Source: MarketsandMarkets; Grand View Research
What Is Genuinely Differentiated
The position. The intersection of hypersonic speed, vertical takeoff, and crewed multi-mission capability is verifiably unoccupied.
The funding structure. Deep-technology aerospace programs are historically killed by funding-cycle timing rather than engineering failure; a cash-generating parent removes that specific failure mode.
The capital discipline. Tranches release only as independent reviewers clear each TRL gate, which aligns investor exposure with verified technical progress rather than with elapsed time.
Section 02 · The Unoccupied Position
Three capabilities exist separately across the industry. None combines them.
Vertical takeoff, hypersonic speed, and crewed multi-mission capability each exist somewhere in the industry today. No aircraft combines all three. The table below shows, program by program, exactly where that intersection stands — and where it is empty.
| Program | What It Has | What It Does Not Have | Status |
|---|---|---|---|
Hermeus Hypersonic | Mach 5+ target; Chimera TBCC engine | Uncrewed; conventional takeoff | ~$500M raised; Mach 1.21 flown May 2026; FAA experimental certificate; DIU contract |
Venus Aerospace Hypersonic | High-speed propulsion via rotating detonation | No integrated airframe; not VTOL | Approximately $70M raised; engine demonstration stage |
Boom Supersonic Supersonic | Crewed; supersonic; passenger scale | Conventional takeoff; not hypersonic | XB-1 supersonic January 2025; Overture airliner and Symphony engine in development |
Spike Aerospace Supersonic | Quiet-supersonic business jet design; low-boom focus | Not hypersonic; conventional takeoff; small capacity | Pre-revenue development stage |
Joby VTOL / eVTOL | VTOL; crewed; certification pathway | Subsonic; short range; small payload | In FAA certification; piloted transition demonstrations |
Archer VTOL / eVTOL | VTOL; crewed; certification pathway | Subsonic; short range; small payload | Midnight in flight test; certification-track; UAE launch targeted 2026 |
Vertical Aerospace VTOL / eVTOL | VTOL; piloted flight testing | Subsonic; short range; small payload | VX4 in flight test; certification-track with aerospace-tier partners |
Lilium VTOL / eVTOL | VTOL; crewed design | Subsonic; operations ceased 2024 — funding, not engineering | Ceased operations in 2024 after failing to close a raise; assets relaunched 2025 |
F-35B Defense | VTOL and supersonic on one airframe | Not hypersonic; not multi-mission at passenger scale | Fielded combat aircraft |
Competitor status as published in company releases and trade press through mid-2026. Boeing, Airbus, Lockheed Martin and Northrop Grumman are not building a comparable configuration; they are the most probable strategic counterparties, partners, licensees or acquirers.
Hermeus · Hypersonic
Has — Mach 5+ target; Chimera TBCC engine
Lacks — Uncrewed; conventional takeoff
~$500M raised; Mach 1.21 flown May 2026; FAA experimental certificate; DIU contract
Venus Aerospace · Hypersonic
Has — High-speed propulsion via rotating detonation
Lacks — No integrated airframe; not VTOL
Approximately $70M raised; engine demonstration stage
Boom Supersonic · Supersonic
Has — Crewed; supersonic; passenger scale
Lacks — Conventional takeoff; not hypersonic
XB-1 supersonic January 2025; Overture airliner and Symphony engine in development
Spike Aerospace · Supersonic
Has — Quiet-supersonic business jet design; low-boom focus
Lacks — Not hypersonic; conventional takeoff; small capacity
Pre-revenue development stage
Joby · VTOL / eVTOL
Has — VTOL; crewed; certification pathway
Lacks — Subsonic; short range; small payload
In FAA certification; piloted transition demonstrations
Archer · VTOL / eVTOL
Has — VTOL; crewed; certification pathway
Lacks — Subsonic; short range; small payload
Midnight in flight test; certification-track; UAE launch targeted 2026
Vertical Aerospace · VTOL / eVTOL
Has — VTOL; piloted flight testing
Lacks — Subsonic; short range; small payload
VX4 in flight test; certification-track with aerospace-tier partners
Lilium · VTOL / eVTOL
Has — VTOL; crewed design
Lacks — Subsonic; operations ceased 2024 — funding, not engineering
Ceased operations in 2024 after failing to close a raise; assets relaunched 2025
F-35B · Defense
Has — VTOL and supersonic on one airframe
Lacks — Not hypersonic; not multi-mission at passenger scale
Fielded combat aircraft
Competitor status as published in company releases and trade press through mid-2026. Boeing, Airbus, Lockheed Martin and Northrop Grumman are not building a comparable configuration; they are the most probable strategic counterparties, partners, licensees or acquirers.
What Is Verifiable Today
The intersection is empty. Hermeus is uncrewed with conventional takeoff. Joby and Archer are VTOL but subsonic and short-range. Boom is crewed and supersonic but takes off conventionally. Vectored-thrust combat aircraft combine VTOL and supersonic flight but are neither hypersonic nor multi-mission at passenger scale. These are public facts about public programs.
What Remains to Be Proven
That the position is reachable. A position can be empty because it is valuable and difficult — or because it is not physically achievable, or because the trade-offs make it uneconomic even if achievable. Each of the three capabilities pushes a design in a different direction, and combining them is multiplicative difficulty, not additive. Establishing whether it can be done is the work this raise funds.
The Position, Stated Plainly
"There is an unoccupied position combining vertical takeoff, hypersonic speed, and crewed multi-mission capability. We believe a toroidal architecture is the most promising route to it. We are at TRL 3, and the capital we are raising funds the work required to establish whether that belief survives contact with analysis and testing. Every subsequent tranche is gated on an independent reviewer clearing the previous one."
Section 03 · The Aircraft
ALT-01 — design parameters, not measured results.
92 m
Outer diameter
680 t
Gross mass
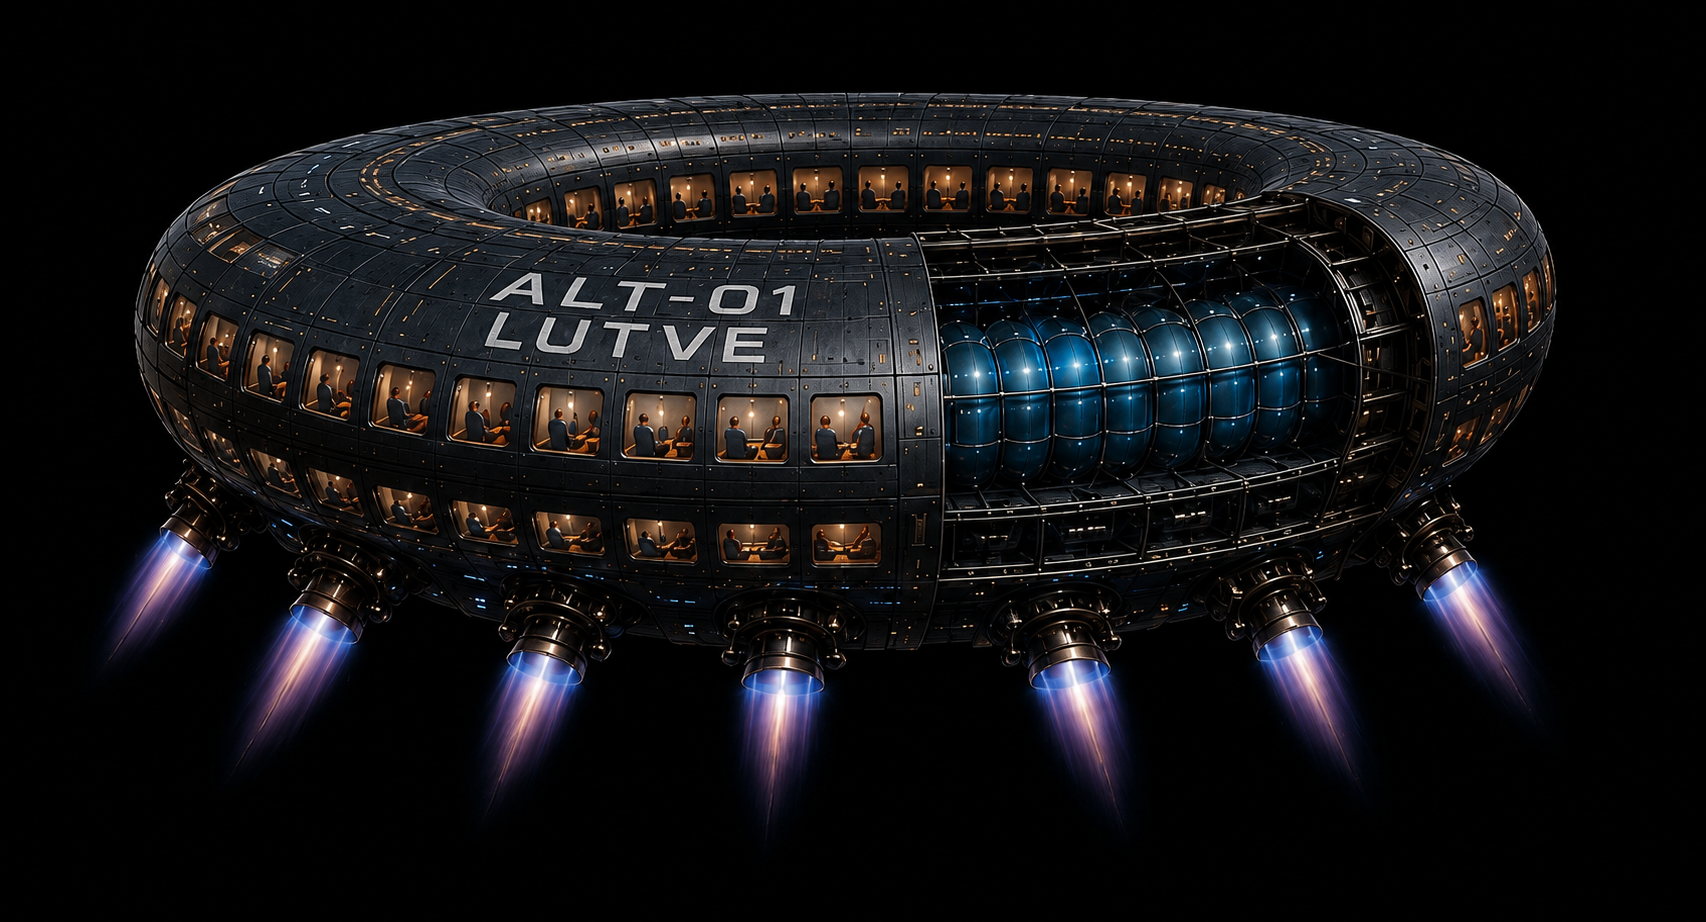
Artist's concept of the ALT-01 general arrangement, configuration per AL-EXD-001 Issue 2. The engine arrangement shown is the intended configuration: eight dual-axis gimbaled nozzles distributed symmetrically around the lower toroidal rim, of which the far side of the ring is occluded.
Configuration
Airframe
Toroidal lift body; the outer ring is the lifting surface; multi-wall toroidal structural hull
Propulsion
Compressed Vortex Propulsion (CVP); hydrogen initially, plasma at scale. The aircraft is both airframe and engine — the toroidal geometry generates the vortex that lifts and drives the structure.
Speed / Ceiling
Mach 6.5 · 100,000+ ft · vertical takeoff and landing
New York to Tokyo in 90 minutes
Capacity
420–550 passengers, or defense, cargo and medevac configurations on the same airframe
Geometry
92 m outer diameter · 21.5 m overall height
Mass
680,000 kg gross takeoff · ~253,000 kg LH₂ · 37% fuel mass fraction
Cruise
950 kN thrust · 38 kg/s LH₂ cruise flow · ~77 kg/s at VTOL phase (≈2× cruise)
Mission Profile
10 min VTOL/transition (12°–45° lift-assisted ascent) · 90 min Mach 6.5 cruise at 100,000 ft · 10 min descent/landing
Three Numbers to Read Carefully
92 metres, 680 tonnes.
The diameter is 15% wider than the 79.8-metre wingspan of an A380; the gross mass exceeds the heaviest aircraft ever flown. That scale follows from the passenger count and hydrogen's volume penalty, not from ambition.
37.2% fuel mass fraction.
Just over a third of takeoff mass is fuel — the most useful single number for explaining why the airframe is sized as it is.
2,000 m/s cruise.
At altitude, where the speed of sound is far lower than at sea level, this is approximately Mach 6.5 at cruise altitude — consistent with the Mach 6+ claim. It is also what puts New York to Tokyo at 90 minutes: a 10,850 km great circle at 2,000 m/s is 90.4 minutes of cruise, with climb, acceleration and descent outside that figure.
Material Specification — AL-CVP-002
Structural Frame
Ti-6Al-4V (Titanium Alloy)
High strength / low weight; rigid under compression
Vortex Channel
Inconel 718
High-temperature / corrosion resistance; resists fatigue from pressure cycling
Thermal Shield
ZrO₂–Y₂O₃ / SiC-CMC
Heat resistance at hypersonic stagnation temperatures
Outer Skin
Carbon Fiber CFRP-7800
Radar-absorbent; high strength-to-weight for aero-elastic bending
Interior Panels
Al-Honeycomb
Fire retardant
Every material is matched to the exact load it carries at Mach 6.5: ceramic where it is hot, titanium where it is compressed, Inconel where it pulses, carbon fiber where it bends.
Hydrogen — The Real Trade
Excellent energy per kilogram — roughly three times jet fuel. Poor energy per litre: even liquefied, about four times the volume for the same energy. That drives large cryogenic tankage and an airport supply chain that does not yet exist at scale.
Section 03b · Flight Time Simulator
Pick any two cities. Watch what the ALT-01 LUTVE's Mach 6.5 does to the clock.
Great-circle distance, flown at the ALT-01's Mach 6.5 cruise target against today's long-haul commercial jet. Vertical takeoff also removes the airport runway from the equation — downtown to downtown.
Distance
10,852 km
ALT-01 · Mach 6.5
1h 30m
Commercial Jet
12h 50m
Time Recovered
11h 19m
Great-circle distance at the 2,000 m/s design cruise (7,200 km/h, ≈Mach 6.5 at 100,000 ft) versus a Mach 0.85 commercial jet plus 30 minutes of terminal, taxi and climb overhead. ALT-01 times are cruise time; vertical takeoff and landing add roughly 20 minutes. Times are design targets at TRL 3 and exclude ATC routing, weather deviation and ground transfer.
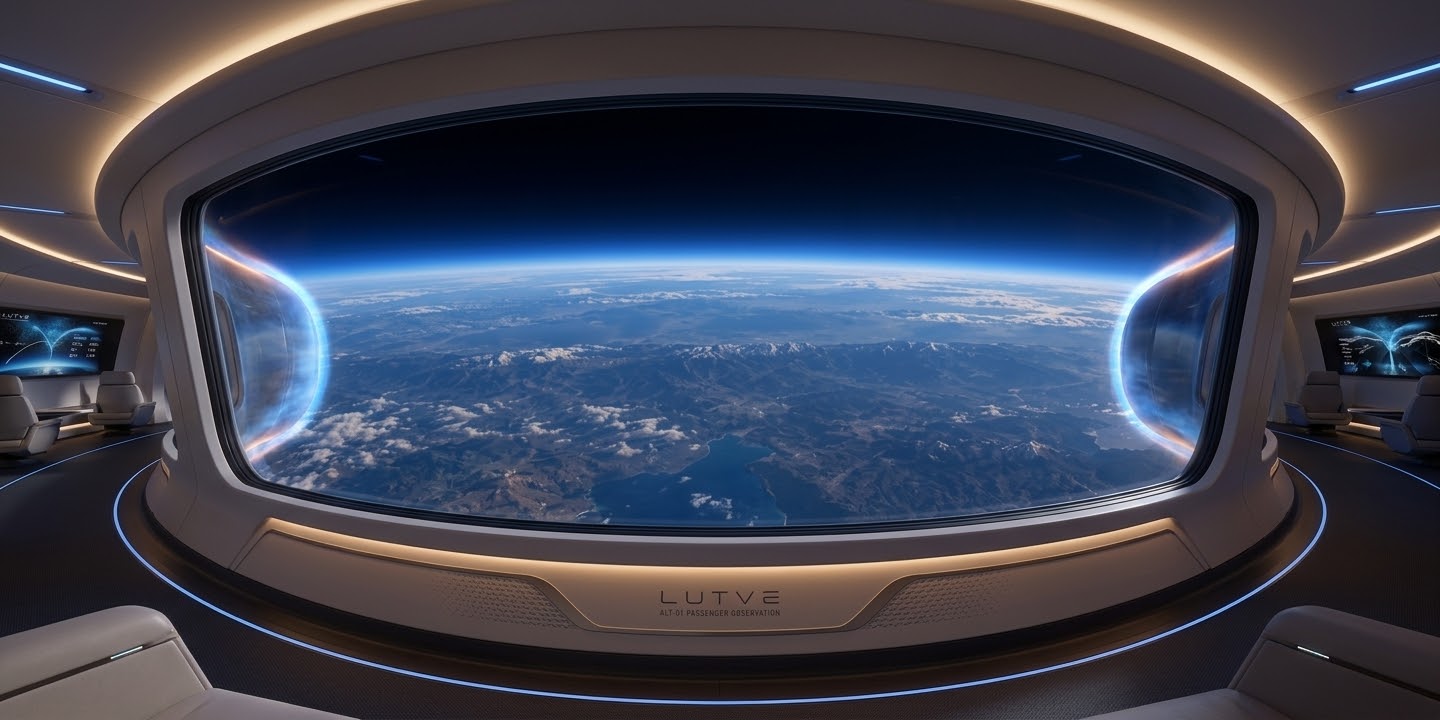
Concept render · passenger deck at 100,000 ft cruise — above 99% of the atmosphere, Earth curvature fully visible. Design targets at TRL 3.
Section 04 · Transition — And the Two-Part Answer
The central engineering question.
"How does it transition?" is the first question any aerospace engineer asks about a VTOL concept. Most VTOL programs that have failed, failed at transition — the handover from vertical to horizontal flight, where airspeed is too low for control surfaces to bite but the aircraft is no longer hovering.
Why the problem is structural
Hover and cruise want opposite things. Hover wants large, slow-moving disc area to move a great deal of air gently, which is why helicopter rotors are enormous. Efficient high-speed cruise wants small frontal area and minimal drag. Any design that does both must carry two propulsion arrangements or use one that reconfigures — and every prior approach pays for that in a different currency.
| Approach | How It Works | The Penalty |
|---|---|---|
Tiltrotor V-22, V-280 | Rotors tilt from vertical to horizontal in flight | Mechanical complexity at the tilt mechanism; heavy; long and costly development |
Vectored thrust Harrier, F-35B | Engine exhaust redirected downward for lift | Very high fuel burn in hover; severe payload and range penalty; ground erosion |
Lift + cruise Most eVTOL designs | Separate rotors for lift, separate propulsion for cruise | Dead weight — lift rotors are carried, unused, through the entire cruise |
Ducted / annular Closest published analogue | Lift fans enclosed within a duct or ring structure | Duct weight; complex internal flow; a long record of promising wind-tunnel results and disappointing flight programs |
Tiltrotor
V-22, V-280
How It Works
Rotors tilt from vertical to horizontal in flight
The Penalty
Mechanical complexity at the tilt mechanism; heavy; long and costly development
Vectored thrust
Harrier, F-35B
How It Works
Engine exhaust redirected downward for lift
The Penalty
Very high fuel burn in hover; severe payload and range penalty; ground erosion
Lift + cruise
Most eVTOL designs
How It Works
Separate rotors for lift, separate propulsion for cruise
The Penalty
Dead weight — lift rotors are carried, unused, through the entire cruise
Ducted / annular
Closest published analogue
How It Works
Lift fans enclosed within a duct or ring structure
The Penalty
Duct weight; complex internal flow; a long record of promising wind-tunnel results and disappointing flight programs
CVP operational cycle — 5 stages
The 360° ring eliminates tip vortices and enables uniform flow capture that conventional forward-facing intakes cannot achieve.
360° Intake
Uniform flow capture around the full circumference. Unlike a forward-facing intake, the ring draws air symmetrically, enabling VTOL without attitude-dependent flow asymmetry.
Multi-Stage Compression
Compression chevron stack raises flow pressure through staged rings. Chevron geometry validated at bench-scale (Stage 1 milestone).
Pulsing Energy-Addition Core
Fuel or plasma injection with pulsed combustion at 500–2,500 Hz. Pulsing improves combustion stability and maximises energy density transfer into the vortex core.
Stabilised Vortex
Torsional lock maintains flow coherence ahead of the exhaust nozzles, minimising turbulence and sustaining the low-pressure region that generates lift across the full 92 m disc.
Vector Thrust Exhaust
Gimbal range ±20°, enabling pitch, yaw and roll authority. Thermal expansion products exit at 2,500–4,500 K through the nozzle array.
The architectural answer
Distributing thrust around a circumference gives differential control authority in every axis without relying on aerodynamic control surfaces — which is precisely what fails during transition. A tiltrotor solves this with heavy mechanical reconfiguration; a lift-plus-cruise design solves it by carrying dead weight. A ring solves it geometrically.
Eight dual-axis gimbaled nozzles
Positioned symmetrically around the lower toroidal rim. The 8-nozzle array is over-actuated relative to the 6 degrees of freedom it controls — providing 2 degrees of redundancy. Loss of a single nozzle does not zero out a control axis; the FCS re-weights the remaining seven in real time.
Sub-5 ms control loop
The flight computer runs a proportional-derivative (PD) feedback loop at under 5 ms latency — fast enough to correct instability before it propagates through the vortex structure. Validated via hardware-in-the-loop simulation at Stage 4.
Tri-Phase transition sequence
VTOL lift-assisted ascent from 12° to 45° over 10 minutes, progressively vectoring nozzles toward horizontal as the vortex field strengthens. The lift burden transfers from direct thrust to the toroidal CVP effect across that window.
Asymmetric load balancing
If sensors detect a load imbalance during transition, the 8-nozzle architecture performs micro-adjustments to individual thrust vectors to maintain 6-DOF stability. Redundancy trigger: emergency Nozzle-to-Vortex dump uses pressurized hydrogen to maintain vortex coherence for a controlled landing.
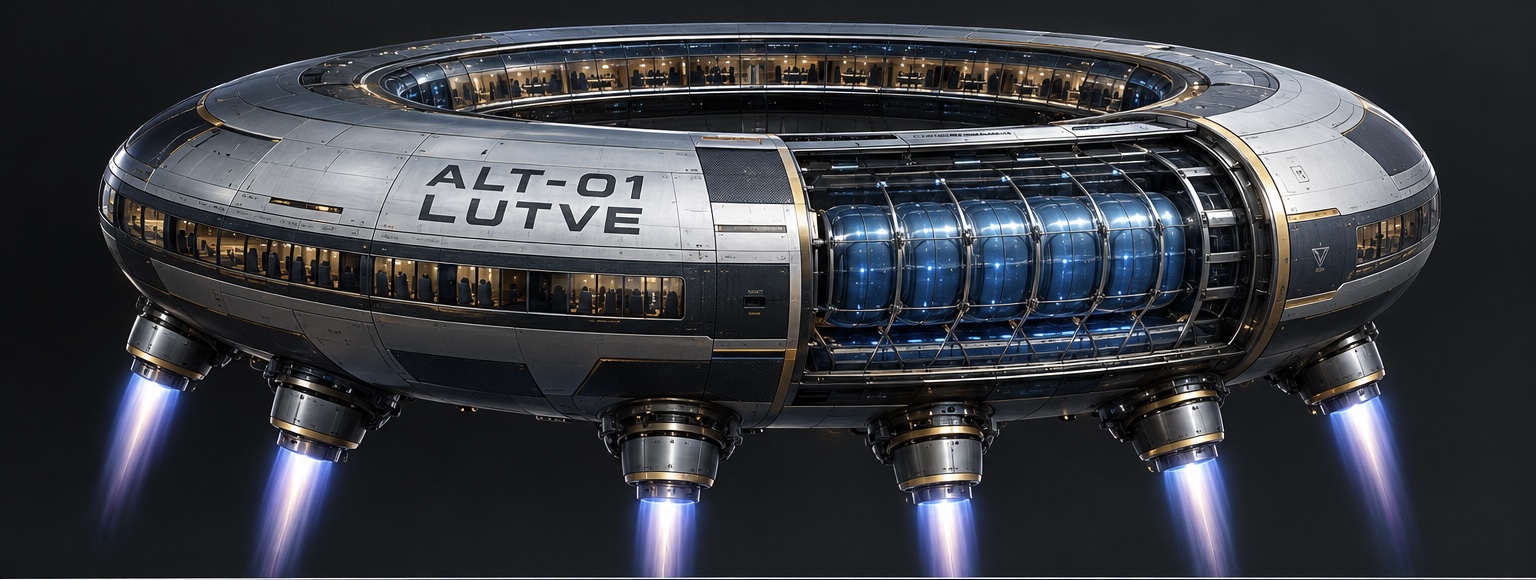
Fig. 4-B
Conceptual configuration — VTOL transition. Cutaway of the toroidal core with the eight-nozzle vectoring array active. Artist's concept; configuration and performance are design targets at TRL 3, not demonstrated hardware.
Designed, Not Yet Demonstrated
What the above establishes is that the design has a coherent control strategy. What it does not establish is that the strategy holds in a real flow field. The control approach is designed, not demonstrated, and validating it through the transition regime is the core of the TRL 3-to-4 program.
Section 05 · Program Maturity and the Funding Gate
TRL 3 today. This next series raise buys the gate to TRL 4.
Technology Readiness Levels are the shared language for program maturity across aerospace and defense. Every technical and government counterparty will locate the program on this ladder before anything else.
1
2
3
4
5
6
7
8
9
TRL 3 is analytical and experimental proof of concept. TRL 4 is component validation in a laboratory environment. Most programs that fail, fail between TRL 4 and TRL 6 — the interval in which laboratory results must survive a real environment.
Measured against the category benchmark
Hermeus was founded in 2018, has raised approximately $500 million, built dedicated test infrastructure, flown three aircraft iterations, and reached Mach 1.21 uncrewed — with its own hypersonic goal still ahead of it. Programs in this category scale on demonstrated evidence, and this raise is scoped accordingly: it funds the TRL 3-to-4 gate, the next unit of independently verifiable progress — not a flying aircraft.
What each phase must produce
Now – Q4 2027
TRL 3 → 4Analytical validation of the propulsion concept; component-level laboratory testing; independent technical review; certification-basis conversation opened with the FAA; first defense research contract
2028 – 2030
TRL 4 → 6Component validation in a relevant environment; subscale demonstrator; experimental airworthiness certificate; supply chain qualification begun
2030 – 2033
TRL 6 → 8Full-scale prototype in an operational environment; production certificate path; a launch customer
2033 – 2036
Exit windowIPO or strategic sale, per company materials
Phase content beyond the Q4 2027 gate follows standard aerospace program structure; milestone definitions past TRL 4 are set by the technical program.
Validation milestone schedule — AL-CVP-002 Appendix D
| Milestone | Objective | Validation Method | Status |
|---|---|---|---|
Stage 1 Bench-Scale Component Test | Validate individual chevron ring compression ratios. | Static pressure testing in lab environment. | In progress |
Stage 2 Integrated Breadboard Test | Confirm stability of the vortex core across the 0.8–1.2 Rossby number band. | High-frequency pressure transducers; LES correlation. | Planned |
Stage 3 Thermal & Structural Cycle | Assess Inconel 718 material resilience to sustained exhaust heat under Coffin-Manson fatigue loading. | Accelerated fatigue cycling in controlled chamber; minimum 100 thermal cycles. | Planned |
Stage 4 Control Loop Latency | Verify <5 ms response for the 8-nozzle thrust-vectoring allocation. | Hardware-in-the-loop (HIL) simulation. | Planned |
Stage 1
Bench-Scale Component Test
Objective
Validate individual chevron ring compression ratios.
Validation Method
Static pressure testing in lab environment.
Status
Stage 2
Integrated Breadboard Test
Objective
Confirm stability of the vortex core across the 0.8–1.2 Rossby number band.
Validation Method
High-frequency pressure transducers; LES correlation.
Status
Stage 3
Thermal & Structural Cycle
Objective
Assess Inconel 718 material resilience to sustained exhaust heat under Coffin-Manson fatigue loading.
Validation Method
Accelerated fatigue cycling in controlled chamber; minimum 100 thermal cycles.
Status
Stage 4
Control Loop Latency
Objective
Verify <5 ms response for the 8-nozzle thrust-vectoring allocation.
Validation Method
Hardware-in-the-loop (HIL) simulation.
Status
Why the Raise Is Gated
Capital releases only as independent reviewers clear each gate, aligning investor exposure with verified technical progress. Funding is tied to what independent reviewers confirm has been achieved, phase by phase.
Latest Update
Houston · October 22, 2026Altareon Group advances the ALT-01 program, with a near-term focus on validation, partnerships and prototype development
Bench-scale testing of the aircraft's compression components is underway, and the company is targeting its TRL 4 gate in the fourth quarter of 2027. Capital and commitments remain tied to independently reviewed, verified technical progress.
"Aviation is running into hard limits on speed, capacity and emissions, and no one has yet combined vertical lift, hypersonic speed and crewed capability in one aircraft. That's the position we intend to lead."Nathan F. Lee, Chief Executive Officer, Altareon GroupRead the full press release (PDF)
Forward-looking statements. ALT-01 performance figures are design targets at TRL 3 and have not been demonstrated. Not an offer to sell or a solicitation of an offer to buy securities.
Section 06 · Path to Market — Sequenced by Proximity to Revenue
One airframe. Four markets.
Structural modularity is what makes four markets reachable from one certification effort. The sequence below is set by how close each market sits to revenue, and each entry point is tied to a funded program phase rather than to a calendar date alone.
| Market | Stated TAM | Entry | Revenue Mechanism | Basis |
|---|---|---|---|---|
Military & tactical | $20–40B | Phase 3 · 2031+ | DoD and NATO procurement; per-unit sales, MRO, and licensing; Future Vertical Lift alignment | DoD FY2026 hypersonic warfare request: $13.4B, including $3.9B in hypersonic research |
Commercial hypersonic | $250B+ | Phase 3–4 | The largest market; per-unit sales, carrier licensing, and royalties | Hypersonic flight $11.4B (2025) → $120B (2035) at 26.5% CAGR; supersonic passenger market $73B by 2035 (Precedence) |
Humanitarian & medevac | $500M+/yr | Phase 3–4 | UN and NATO logistics; ESG impact-bond co-investment | UN/NATO contract cycles; ESG-aligned capital |
Extreme environment & space | $100B+ | Phase 4 · 2032+ | Joint venture with energy majors; polar, lunar, and asteroid long-range upside | Polar resource access; lunar/asteroid mining long-range optionality |
Phase 1 (2027–28, $12M) functional prototype and patent filing · Phase 2 (2029–30, $13M) contracts negotiated, factory infrastructure, TRL 6 validated · Phase 3 (2031, $950M) 30 units/yr capacity, first commercial and defense deliveries · Phase 4 (2032–36, $600–700M/yr) 50–60 aircraft/yr. Market figures are total-addressable estimates, not LUTVE revenue.
Military & tactical
Stated TAM
Entry
Phase 3 · 2031+
Revenue Mechanism
DoD and NATO procurement; per-unit sales, MRO, and licensing; Future Vertical Lift alignment
Basis
DoD FY2026 hypersonic warfare request: $13.4B, including $3.9B in hypersonic research
Commercial hypersonic
Stated TAM
Entry
Phase 3–4
Revenue Mechanism
The largest market; per-unit sales, carrier licensing, and royalties
Basis
Hypersonic flight $11.4B (2025) → $120B (2035) at 26.5% CAGR; supersonic passenger market $73B by 2035 (Precedence)
Humanitarian & medevac
Stated TAM
Entry
Phase 3–4
Revenue Mechanism
UN and NATO logistics; ESG impact-bond co-investment
Basis
UN/NATO contract cycles; ESG-aligned capital
Extreme environment & space
Stated TAM
Entry
Phase 4 · 2032+
Revenue Mechanism
Joint venture with energy majors; polar, lunar, and asteroid long-range upside
Basis
Polar resource access; lunar/asteroid mining long-range optionality
Phase 1 (2027–28, $12M) functional prototype and patent filing · Phase 2 (2029–30, $13M) contracts negotiated, factory infrastructure, TRL 6 validated · Phase 3 (2031, $950M) 30 units/yr capacity, first commercial and defense deliveries · Phase 4 (2032–36, $600–700M/yr) 50–60 aircraft/yr. Market figures are total-addressable estimates, not LUTVE revenue.
Mission use cases — click a market to see what a delivery actually does
Contested logistics, compressed
A priority resupply across the Pacific that occupies a C-17 for eleven hours is a 90-minute mission. Timeline compression turns days of theater logistics into hours.
High-altitude transit
Cruise at 100,000 ft sits above weather and commercial traffic — an efficient corridor for moving critical cargo and priority personnel between regions.
Golden-hour medevac
Casualty evacuation from a forward base directly to continental-US surgical care inside the golden hour — a mission profile no rotorcraft or fixed-wing asset can fly today.
Use cases are mission concepts derived from the ALT-01 design targets at TRL 3 — vertical takeoff, Mach 6 cruise, 100,000 ft ceiling. Defense applications are subject to U.S. export controls (ITAR/EAR): no technical data is disclosed on this site, and military mission details are available only through export-controlled documentation to authorized recipients.
What the sequencing is worth
Four revenue lines from one certification effort. The irreducible cost in a new aircraft program is proving the airframe. Modularity designed in — rather than bolted on later — amortizes that one proof across military, commercial, humanitarian, and extreme-environment demand.
Military first because it tolerates immaturity. Defense buys progress toward capability; commercial aviation buys certified aircraft with published performance. Military airworthiness is a separate and faster path than civil certification. The organizations funding the run-up (DARPA, AFRL, DIU, NASA SBIR/STTR) do so with non-dilutive capital — the DoD alone requested $13.4B for hypersonic warfare programs in FY2026.
Each phase funded against the last. Capital scales with demonstrated progress. Phase 3's $950M is committed only after TRL 5/6 validation and at least one signed letter of intent, which means the largest deployment in the plan is the one most protected by evidence.
Section 06a · Business Case Portfolio
Twelve business cases — where the money comes from.
Four verticals, three cases each. Every figure carries an honest label: a published third-party number, a LUTVE design target at TRL 3, or a derived illustration from our model — so you always know what kind of claim you are reading.
Same-day transatlantic
Sell the trip no airline can sell today: New York to London and back in a single business day — with up to five crossings per airframe every day.
~$0.8M
ILLUSTRATIVERevenue per crossing at today's average business fare
~$1.5B
ILLUSTRATIVEAnnual revenue potential per airframe at five crossings a day
~12 h
TARGETSaved per round trip, plus a hotel night
$12,000
BENCHMARKConcorde's round-trip fare — proof travelers pay for speed
07:00 NY
Depart JFK — vertical takeoff from a standard gate
13:06 LDN
Arrive London — about 66 minutes in the air
14:30–17:00
The meeting — a full afternoon on the ground
18:30 LDN
Depart London; home in New York by mid-afternoon
Decision on the table
Airframer partner and a launch airline co-fund a New York–London route-economics study, with a letter of intent timed to the first independent verification gate.
The fifteen-hour flight becomes two
Turn the world's longest flights into a two-hour product — and let one airframe do the Pacific work of four widebodies.
~$0.8M
ILLUSTRATIVERevenue per crossing at today's average business fare, ~370 seats
~$1.2B
ILLUSTRATIVEAnnual revenue potential per airframe at four crossings a day
~13 h
TARGETSaved each way, Los Angeles–Sydney
$5,706
BENCHMARKAverage Los Angeles–Sydney business round trip today
DAY 1 AM
Depart Los Angeles — standard gate; climb over the Pacific
+2 h
Arrive Sydney — about 120 minutes instead of 15 hours
DAY 1
Work in Sydney — a full working day, no lost travel day
DAY 2
Home — no overnight flight in either direction
Decision on the table
Airframer partner and a Pacific launch carrier commission a joint Los Angeles–Sydney and San Francisco–Shanghai study, with a letter of intent at the first verification gate.
Satellites on demand
Put a replacement satellite on orbit within one working day of the order — launched from an airport, by an aircraft that earns its keep every other day of the year.
$7.5M
BENCHMARKMarket price of a dedicated small launch today
0
TARGETLaunch pads to build, defend, or schedule
< 12 h
TARGETOrder to orbit, versus a 27-hour record
~8×
ILLUSTRATIVEUpper-stage release speed vs a subsonic carrier
H + 0
Launch order — satellite already mated to its upper stage
H + 6
Loaded at the airfield — no pad, no range slot
H + 7.5
Released at Mach 6+ — over the ocean at cruise altitude
H + 8
On orbit — within the same working day
Decision on the table
Space Force and an upper-stage partner co-fund a release-and-integration study, with a demonstration slot reserved after the TRL 6 flight program.
Labels: BENCHMARK = published third-party figure · TARGET = LUTVE design target at TRL 3 · ILLUSTRATIVE = derived from our model, not a forecast. Timeline times include roughly 20 minutes of VTOL ascent and descent; revenue figures are per-airframe potential, not committed sales. Condensed from the internal business-case portfolio, AL-BCP-001 · Issue 2 · October 2026.
Section 06b · Market Sizing — The Honest Spread
Adjacent forecasts diverge by orders of magnitude. We show them all.
Every figure below is a published, sourced forecast for a category adjacent to LUTVE. The spread within a single category — eVTOL alone spans from $4.67B to $216B — is driven entirely by scope: what's counted, what year, and whether it includes infrastructure. This is why we state the figure, the source, and what it includes, rather than picking one.
Published forecasts, $B (log scale to show spread)
| Category | Source | Year | Value | CAGR |
|---|---|---|---|---|
| Hypersonic flight | MarketsandMarkets | 2030 | $1.15B | 5.7% |
| Hypersonic flight | Fortune Business Insights | 2034 | $5.86B | 9.9% |
| Hypersonic flight | Precedence Research | 2035 | $120B | 26.5% |
| eVTOL | Mordor Intelligence | 2030 | $4.67B | — |
| eVTOL | MarketsandMarkets | 2035 | $5.08B | 12.3% |
| eVTOL | Grand View Research | 2030 | $28.6B | 54.9% |
| eVTOL | Precedence Research | 2035 | $216B | — |
| Supersonic (comm.) | Precedence Research | 2035 | $73.4B | — |
| Hydrogen aircraft | MarketsandMarkets | 2030 | $7.4B | 28.9% |
| Hydrogen aircraft | Grand View Research | 2030 | $9.1B | 41% |
Source
MarketsandMarkets
Year
2030
Value
$1.15B
CAGR
5.7%
Source
Fortune Business Insights
Year
2034
Value
$5.86B
CAGR
9.9%
Source
Precedence Research
Year
2035
Value
$120B
CAGR
26.5%
Source
Mordor Intelligence
Year
2030
Value
$4.67B
CAGR
—
Source
MarketsandMarkets
Year
2035
Value
$5.08B
CAGR
12.3%
Source
Grand View Research
Year
2030
Value
$28.6B
CAGR
54.9%
Source
Precedence Research
Year
2035
Value
$216B
CAGR
—
Source
Precedence Research
Year
2035
Value
$73.4B
CAGR
—
Source
MarketsandMarkets
Year
2030
Value
$7.4B
CAGR
28.9%
Source
Grand View Research
Year
2030
Value
$9.1B
CAGR
41%
What the spread tells you
A market forecast that varies by 46× across reputable sources is not a number you can build a revenue plan on. It is a signal that scope, not conviction, is doing the work. LUTVE's revenue plan is built bottom-up from contracted defense research and named launch customers — not top-down from a TAM.
How LUTVE sizes its own opportunity
Near-term: addressable value of defense research and prototyping contracts over 3–5 years, with a target win rate against a named list of DoD programs. Long-term: the $88.4B delivery-value base case, conditional on clearing each TRL gate. Both are stated with their assumptions, not asserted as certainty.
Sources: Boeing Commercial Market Outlook 2026–2045 · Oliver Wyman Global Fleet & MRO Forecast 2026–2036 · Precedence Research · MarketsandMarkets · Grand View Research · Fortune Business Insights · Mordor Intelligence · DoD FY2026 Budget Submission. All figures are published third-party forecasts; LUTVE does not endorse a single point estimate.
Section 07 · The Offering and Use of Proceeds
$25–50 million, released only as independent reviewers clear each gate.
| Term | As Structured |
|---|---|
Initial raise | $25–50 million, milestone-gated |
Gate | TRL 4, targeted Q4 2027 — the milestone gate to the Series A |
Release mechanism | Capital unlocks as independent reviewers clear each TRL gate |
Sponsor funding | Program self-funded through ALTAREON's cash-generating energy platform |
Stated base case | $88.4B in ten-year delivery value, conditional on the technology clearing its gates |
Exit | IPO or strategic sale, targeted 2033–2036 |
Initial raise
As Structured
$25–50 million, milestone-gated
Gate
As Structured
TRL 4, targeted Q4 2027 — the milestone gate to the Series A
Release mechanism
As Structured
Capital unlocks as independent reviewers clear each TRL gate
Sponsor funding
As Structured
Program self-funded through ALTAREON's cash-generating energy platform
Stated base case
As Structured
$88.4B in ten-year delivery value, conditional on the technology clearing its gates
Exit
As Structured
IPO or strategic sale, targeted 2033–2036
What the first tranche must produce
- ›Analytical validation of the propulsion concept
- ›Component-level laboratory testing
- ›Independent technical review at the gate
- ›Certification-basis conversation opened with the FAA
- ›First defense research contract
How the opportunity is measured at TRL 3
At this stage of maturity, the meaningful measures are the addressable value of defense research and prototyping contracts over the next three to five years, and a target win rate against a named list of programs. Those numbers are built bottom-up from contracted and named programs — not top-down from a market forecast — and reported against as the program advances.
What the Structure Removes
Dependence on venture funding cycles — the failure mode that historically kills deep-technology aerospace programs more often than engineering failure does.
What It Does Not Remove
Exposure itself. The program's funding capacity is tied to energy cash flow. That is a more predictable source than venture sentiment, but it is a real exposure, and it is modelled explicitly in the program's downside case.
Section 08 · Principal Risks
The material risks, stated plainly.
The following are the risks the program considers material, together with the mitigation currently in place. We publish them because they define the program's real shape — and because credibility in this category is built on candor.
| Risk | Description | Mitigation |
|---|---|---|
Technical — propulsion | Compressed Vortex Propulsion is unproven at TRL 3. No air-breathing engine covers takeoff through Mach 6 without a combined-cycle or novel architecture. | Milestone gating; independent technical review at each gate; capital released only on clearance |
Technical — transition | VTOL-to-forward-flight transition is where most VTOL programs have historically failed. | Priority focus of the TRL 3–4 analytical work |
Certification | No existing certification basis fits this configuration. Special conditions development is a multi-year program in itself. | Defense-first sequencing; open the FAA conversation early rather than late |
Capital | The category benchmark suggests hundreds of millions of dollars to reach a flying high-speed demonstrator. | Energy platform cash flow; staged raises tied to gates; defense contract revenue |
Schedule | Aerospace programs routinely overrun. The 2033–36 exit window assumes gates clear roughly on time. | Publish milestone dates and report against them transparently |
Supply chain | Qualified aerospace suppliers are capacity-constrained, and qualifying new ones takes years. | Design around existing certified subsystems wherever possible |
Regulatory / ITAR | Defense configurations restrict who may receive technical data, including investors and employees. | Counsel review of all external materials; documented information-handling procedure |
Talent | Hypersonics and VTOL expertise is scarce and concentrated in a handful of organizations. | Partnerships and advisory relationships; realistic hiring timelines in the plan |
Correlation | The energy platform funds the aerospace program, so a sustained energy downturn would affect both simultaneously. | Funding capacity treated as scenario-dependent; downside case modelled explicitly |
Technical — propulsion
Description
Compressed Vortex Propulsion is unproven at TRL 3. No air-breathing engine covers takeoff through Mach 6 without a combined-cycle or novel architecture.
Mitigation
Milestone gating; independent technical review at each gate; capital released only on clearance
Technical — transition
Description
VTOL-to-forward-flight transition is where most VTOL programs have historically failed.
Mitigation
Priority focus of the TRL 3–4 analytical work
Certification
Description
No existing certification basis fits this configuration. Special conditions development is a multi-year program in itself.
Mitigation
Defense-first sequencing; open the FAA conversation early rather than late
Capital
Description
The category benchmark suggests hundreds of millions of dollars to reach a flying high-speed demonstrator.
Mitigation
Energy platform cash flow; staged raises tied to gates; defense contract revenue
Schedule
Description
Aerospace programs routinely overrun. The 2033–36 exit window assumes gates clear roughly on time.
Mitigation
Publish milestone dates and report against them transparently
Supply chain
Description
Qualified aerospace suppliers are capacity-constrained, and qualifying new ones takes years.
Mitigation
Design around existing certified subsystems wherever possible
Regulatory / ITAR
Description
Defense configurations restrict who may receive technical data, including investors and employees.
Mitigation
Counsel review of all external materials; documented information-handling procedure
Talent
Description
Hypersonics and VTOL expertise is scarce and concentrated in a handful of organizations.
Mitigation
Partnerships and advisory relationships; realistic hiring timelines in the plan
Correlation
Description
The energy platform funds the aerospace program, so a sustained energy downturn would affect both simultaneously.
Mitigation
Funding capacity treated as scenario-dependent; downside case modelled explicitly
The Correlated Exposure
One exposure is structural rather than technical. The self-funding structure replaces dependence on venture funding cycles with exposure to energy cash flow — a more predictable source, but a real one. The program treats that exposure explicitly, modelling a sustained energy downturn in its downside case rather than presenting the structure as removing all funding risk.
Section 09 · Leadership
Who is building this.
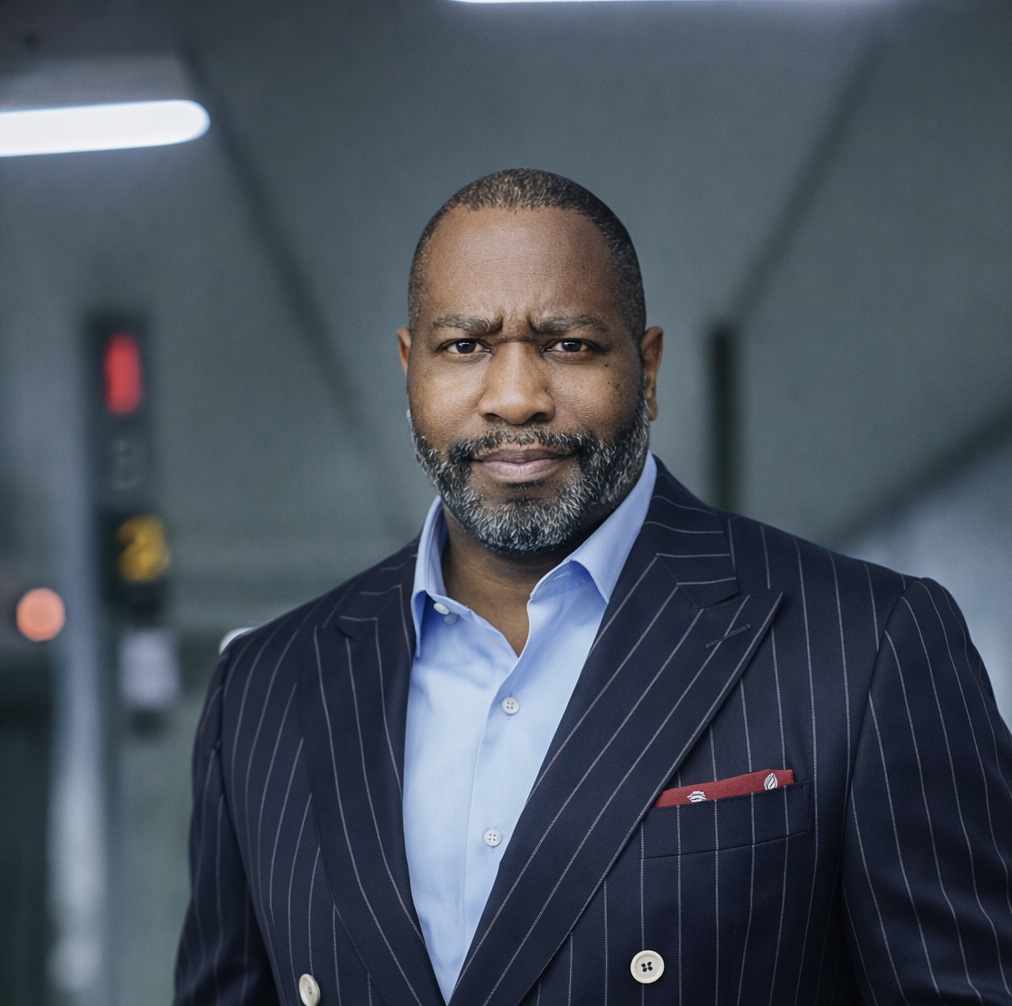
Nathan F. Lee
Chief Executive Officer · ALTAREON Group
Nathan F. Lee began his career in the United States Navy, working on top secret naval intelligence and counter-intelligence systems.
In the twenty-five years since, he has worked at the intersection of engineering, energy, and technology — advising corporations, engineering organizations, and institutional clients on technology transformation, capital programs, operational performance, and energy infrastructure.
That work spans digital transformation, engineering and technology consulting, capital program development, production optimization, and the development of AI technologies applied to industrial and engineering problems — a range covering technical development, corporate strategy, operations, investment, and executive leadership.
What connects the sequence is a single motivation: bringing innovation and creativity to bear on the problems that matter most, and building solutions to the world's most complex challenges.
investrelations@altareongrp.com
Section 10 · Investment Terms
A fixed return, on fixed dates, secured against the program.
Most early aerospace investment asks you to buy equity in an outcome that may be a decade away. This one does not.
LUTVE is raising $25–50 million in milestone-gated tranches; the initial $25 million tranche is a senior secured development note to fund ALT-01 from Technology Readiness Level 3 to TRL 4. The instrument is non-convertible and pays a contracted multiple of principal on three fixed dates, ending at final maturity in 2034. It is secured by a first lien on the program's intellectual property and assets. Investors also receive warrants for 3.0% of fully diluted equity — their participation if the program succeeds.
Open to verified accredited investors only| The offering at a glance | Detail |
|---|---|
Instrument | Senior secured development note — non-convertible, repaid in cash |
Raise | $25–50 million, milestone-gated; the initial $25 million note funds ALT-01 from TRL 3 to TRL 4 |
Return | A contracted multiple of principal on three fixed dates, final maturity 2034 |
Security | First lien on the program’s intellectual property and assets |
Parent guarantee | The ALTAREON parent guarantee covers the final 2034 tranche |
Warrant | 3.0% of fully diluted equity at a $200M pre-money strike |
Prepayment | Greater of the scheduled balance or a 1.75× minimum — prepayment shortens duration and raises realized IRR |
Gate protection | A missed gate delays payment rather than triggering default — a standstill, not an acceleration |
Eligibility | Verified accredited investors only under Rule 506(c) — minimums of $200,000 (individuals) and $1,000,000 (entities) accepted for verification |
Instrument
Detail
Senior secured development note — non-convertible, repaid in cash
Raise
Detail
$25–50 million, milestone-gated; the initial $25 million note funds ALT-01 from TRL 3 to TRL 4
Return
Detail
A contracted multiple of principal on three fixed dates, final maturity 2034
Security
Detail
First lien on the program’s intellectual property and assets
Parent guarantee
Detail
The ALTAREON parent guarantee covers the final 2034 tranche
Warrant
Detail
3.0% of fully diluted equity at a $200M pre-money strike
Prepayment
Detail
Greater of the scheduled balance or a 1.75× minimum — prepayment shortens duration and raises realized IRR
Gate protection
Detail
A missed gate delays payment rather than triggering default — a standstill, not an acceleration
Eligibility
Detail
Verified accredited investors only under Rule 506(c) — minimums of $200,000 (individuals) and $1,000,000 (entities) accepted for verification
The contracted base-case return on principal — paid in cash on three fixed dates, not projected from program performance.
Return and payback — base case at 2.5×
Returns are contracted at close, not projected from program performance. Payback falls in 2032 in every case.
| Date | Event | Detail |
|---|---|---|
2030 | First redemption | Returns 30% of the total |
2032 | Payback | Principal returned in full — in every case |
2034 | Final maturity | Remaining balance, covered by the parent guarantee |
2030
Event
First redemption
Detail
Returns 30% of the total
2032
Event
Payback
Detail
Principal returned in full — in every case
2034
Event
Final maturity
Detail
Remaining balance, covered by the parent guarantee
What sits on top of the return figures
Warrants
The 3.0% fully diluted position at a $200M pre-money strike sits entirely on top of the multiples above. If the program reaches its exit window, that is where the asymmetry is.
Early redemption upside
If the company prepays, it pays the greater of the scheduled balance or a 1.75× minimum. Prepayment shortens duration and raises realized IRR.
Non-convertible, deliberately
A convertible note gives the investor equity on conversion. This structure pays cash on fixed dates instead — an investor knows the return and the timing at close, and the company preserves ownership by never issuing the equity.
Capital releases against verified progress
Tranches unlock only when an independent reviewer has cleared the preceding technical gate. This removes a well-documented pattern in deep-technology programs — raising against a milestone, missing it, and spending the money anyway.
Funded by an operating business
The aerospace program is funded through ALTAREON’s cash-generating energy platform. Deep-technology aerospace programs are historically killed by funding-cycle timing rather than engineering failure — a cash-generating parent removes that failure mode.
The Energy Platform — Described
What it is. ALTAREON’s energy investment platform is the Group’s operating business: a completely separate capital raise, with its own investors, its own mandate across the energy and space sectors, and its own terms. Investors in this note are not investors in the platform.
What it does here. The platform’s cash flow funds the aerospace program between rounds — the reason this program’s survival does not depend on venture sentiment — and the ALTAREON parent guarantee behind the final 2034 maturity is backed by that same cash flow.
What it does not do. It does not remove exposure. Because funding capacity is tied to energy cash flow, correlation is published as a principal risk in Section 08 and modelled explicitly in the program’s downside case.
What the capital funds
The program is at TRL 3 — analytical and experimental proof of concept. This raise funds the gate to TRL 4, targeted Q4 2027 — the next unit of independently verifiable progress.
This offering is available to verified accredited investors. Request the offering documents and we will begin verification.
Request AccessReturn figures are contracted at close and depend on issuer performance; they are not a forecast of program results. Nothing on this page constitutes an offer to sell or a solicitation to buy securities. Principal risks are stated in the Risk section above. Subscription documents and the data room are provided after accreditation verification.
Section 11 · Frequently Asked Questions
The questions investors ask us.
Straight answers on structure, security, and timing — consistent with the terms in Section 10.
Early aerospace equity asks investors to price an outcome a decade away. This instrument instead contracts a fixed multiple of principal on three fixed dates, secured by a first lien on the program's intellectual property and assets. The warrants for 3.0% of fully diluted equity are where investors take the equity-style upside — participation if the program succeeds — without pricing it today.
Section 12 · Investor Center
$25–50 million seed round.
Milestone-gated tranches. Capital releases only as independent reviewers clear each TRL gate. Qualified investors and strategic partners may request full data room access below.
Available Material
Investor Memorandum
ALT-01 LUTVE · AL-EXD-001 · Issue 2 · October 2026
Submit the access request — the memorandum unlocks here automatically once your qualification review clears.
Strictly confidential — for qualified institutional investors only, following accreditation review. All LUTVE specifications are design targets at TRL 3. Nothing here constitutes an offer to sell securities.
Request Data Room Access
Any accreditation documents requested during qualification review are used solely for that review, held in access-controlled private records, and deleted on request if the review is not completed.